Financial planning – vital for business start-up
The heart of every business plan is the financial plan. It outlines how the business is expected to develop, whether the start-up is economically viable, and how much capital is required. It provides founders with the best approach.
This article is part of the special feature GründerNavi – for founders and young companies
Basically, financial planning covers four areas : capital requirements , financing , profitability and liquidity.
1. Capital requirements planning
First, the capital requirements should be carefully planned . This includes all financial resources needed to cover living expenses and business operations . When calculating business capital requirements, it's important to remember that costs are incurred before revenues are generated . These can include start-up expenses such as consulting fees , business registration costs , and entry in the commercial register . And, of course, investments in business equipment are also essential.
Since profits are usually not yet sufficient during the start-up phase , it is important to determine the ongoing costs and include them in the company's capital requirements . There are variable costs , which depend on revenue and include, for example, material costs . Fixed costs remain constant regardless of revenue. These include salaries , rent , and interest.
2. Financing plan
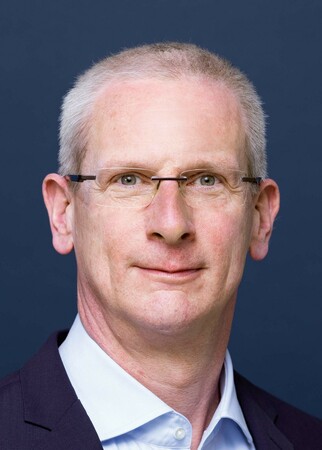 Dr. Andreas Houben, Head of Products and Marketing at TARGOBANK AG. Photo: © TARGOBANK
Here, the financing options are listed. Sufficient equity capital should be available to cover the capital requirements . This can be supplemented by longer-term debt capital , such as bank loans . In addition, there is government financing available , for example from the KfW (German Development Bank).
3. Profitability calculation
Profitability analysis shows whether and when the newly founded business will operate profitably . To determine this, two elements must be included: sales planning , based on pricing , and the profit and loss statement . These should be supplemented by other business metrics such as contribution margin analysis.
A comparatively difficult task is realistically forecasting future sales . Industry knowledge is essential for this; banks or chambers of commerce, which often have access to current industry studies, can be helpful. To produce profitably, however, founders must consider not only competitors' prices and customers' willingness to pay when calculating prices , but above all their own costs. In the second part, the profit and loss statement, monthly expenses are compared to planned revenues . The subsequent contribution margin calculation determines the point at which the business becomes profitable ( break-even point ). The contribution margin is the amount available to cover fixed costs. Once all costs are covered, the break-even point is reached!
Quote: "If you take your time and thoroughly develop your financial plan, you have taken an important step on the path to self-employment." Dr. Andreas Houben , Head of Products and Marketing at TARGOBANK AG.
4. Liquidity planning
Liquidity planning provides an overview of projected solvency and identifies potential funding gaps . Early detection is crucial for taking timely countermeasures. Liquidity planning incorporates gross revenues , initial capital , start-up expenses , investments , personal withdrawals , interest payments , and loan repayments . It should be updated regularly and include a buffer to cover living expenses.
Checklist: Financial planning in four steps
Founders should consider these points in their financial planning
1. Capital requirements planning
1.1. Private capital requirements: Monthly/annual living expenses including reserves for unforeseen events (accident, illness)
1.2. Operating capital requirements: Capital requirements for acquisitions, start-up costs for the start-up of operations and a liquidity reserve during the start-up phase
• Founding expenses (one-off; business registration, entry in the commercial register, notary, consulting fees, patent application fees)
• Investments (office equipment, machinery, work materials, marketing)
• Running costs – Variable costs (materials, raw materials, transport, etc.) – Fixed costs (salaries, rent, leasing costs, IT costs, etc.)
2. Financing plan
2.1. Equity
2.2. Debt capital
3. Profitability calculation for at least three financial years:
Estimation of sales, costs and profit
3.1. Sales planning
3.2. Profit and Loss Account (P&L)
3.3. Calculating the break-even point
(Break-even point) using contribution calculation
4. Liquidity planning for at least three financial years
Estimation of monthly payments from gross sales, start-up capital, etc.
Estimation of monthly fixed and variable costs (materials, personnel, rent, etc.), investment costs, repayment costs and interest payments for loans
Calculation of monthly liquidity reserve
More information and calculation examples can be found here!
CONCLUSION
Capital requirements planning – How much money do you need to get started? Tip: Don't forget your own salary and plan for a buffer to be prepared for unforeseen events.
Financing plan – Where does the money come from? Tip: Cost-cutting is a very cost-effective form of financing.
Profitability calculation – Looking to the future with a targeted approach Tip: Start your own small market research on product and price.
Liquidity planning – Keep an eye on your liquid assets. Tip: Update regularly and plan for a buffer.
DHB is now also available digitally! Simply click here and register for the digital DHB!
Text:
Claudia Stemick /
handwerksblatt.de


Write a comment